Conagra (CAG): A Stock You Might Want to Skip for Now
Conagra Brands (NYSE: CAG) is a familiar name in U.S. households—with brands like Birds Eye, Slim Jim, Healthy Choice, and Chef Boyardee stocked in nearly every grocery aisle. Headquartered in Chicago, the company is well-known and pays a solid dividend but not every popular consumer stock deserves a spot in your portfolio right now.
Stock Performance: Struggling to Keep Up
-
Over the past year, CAG is down around 30%, significantly underperforming the S&P 500.
-
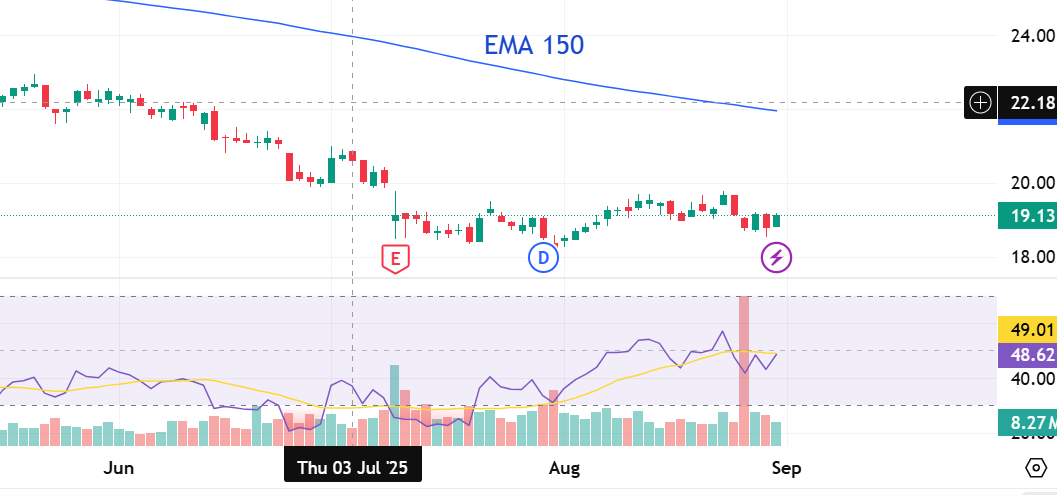
In late August, the stock hovered near a 13-year low, falling off by approximately 40% from its recent high of $33.24.
-
Despite small gains on some days, trading volume remains below average, signaling a lack of strong investor interest.
What's Dragging It Down?
-
Weak Sales and Margin Pressures
-
In Q4 2025, net sales dropped 4.3%, while organic sales slipped 3.5%.
-
Adjusted EPS of $0.56 missed estimates of $0.58, and full-year guidance tops out at just $1.85—well below analyst projections.
-
Inflation, and particularly tariffs, are eating into margins, with the cost of goods sold rising about 7%, including a 3% hit from tariffs.
-
-
Unimpressive Outlook
-
The company guided for flat to slightly negative sales growth (–1% to +1%) and narrowing margins around 11–11.5%.
-
Management plans to manage costs and invest in frozen food and snack segments, but execution risks remain real.
-
-
Industry and Technical Headwinds
-
CAG has lagged peers like Kraft and General Mills and remains in a weak downtrend.
-
Zacks rates it a "Strong Sell," citing consistent earnings misses and falling analyst estimates.
Meanwhile, competitors like Simply Good Foods are thriving by aligning with current health trends and new consumer preferences.
-
Wrap-Up: Familiar Isn't Always Safe
Conagra offers recognizable brands and a strong dividend, but the core business is under strain. Sluggish sales, squeezed margins, heavy tariffs, and falling consumer sentiment point to a company in transition, not a clear turnaround play. It may look cheap, but it lacks the momentum or fundamentals needed for a confident buy right now.
If you want exposure to the food sector, it might be smarter to wait, perhaps for a better entry point, improved margin outlook, or clear signs the company is gaining strength again.
Disclaimer
This article is for educational and informational purposes only. It is not a buy/sell recommendation, nor should it be taken as financial advice. Always consult a qualified financial advisor before making investment decisions.