Defense in Demand: Could Northrop Grumman Be the One to Watch?
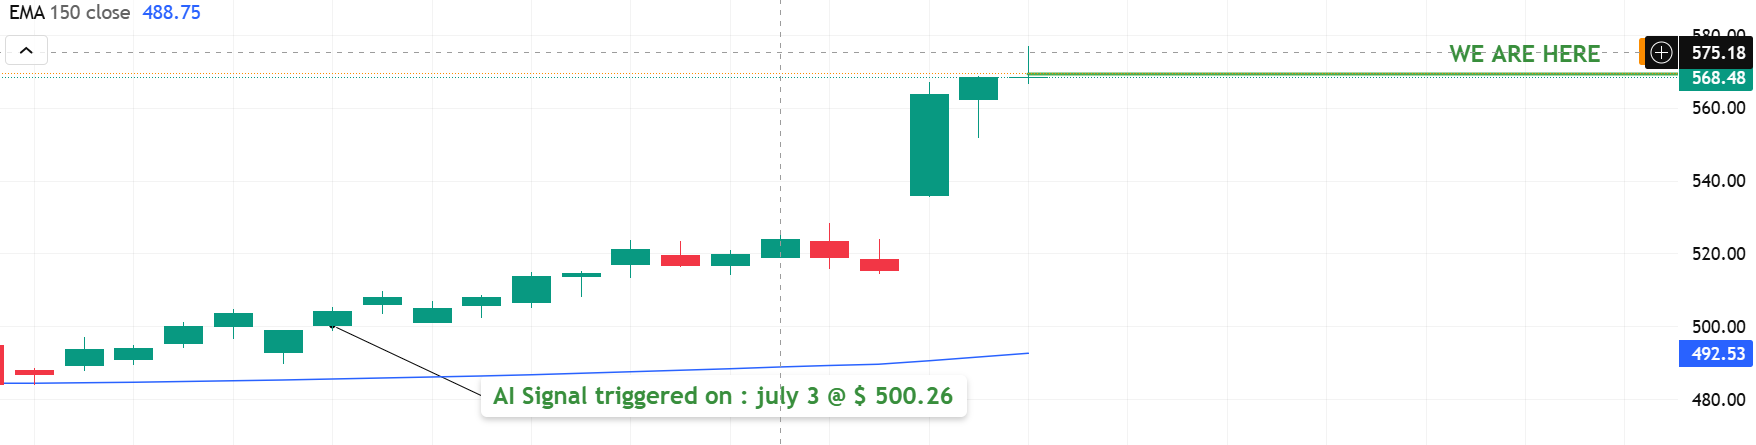
Over the past 15 days, NOC has rallied from ~$492 to ~$570, driven by strong Q2 earnings and global defense demand. With robust technical momentum and renewed guidance, a smart, phased Buy strategy from the $492 base makes sense now—ideal for medium‑term investors.
1. Company Snapshot
Ticker / Sector / Market Cap: NOC, Aerospace & Defense, ~$80 billion.
Revenue Streams: Aeronautics, Mission Systems, Defense Systems, Space & Launch programs (including B‑21, Sentinel, Antares).
Backlog & Contracts: ~$89.7 billion order backlog; contract awards of $7.4 billion in Q2.
2. Why Now?
Earnings Beat: Q2 revenue $10.35 b vs. $10.05 b expected (+1%), EPS $8.15 vs. $6.86 (+19%).
Guidance Raised: 2025 EPS now projected at $25.00–$25.40 and free cash flow $3.05–$3.35 b.
Macro Tailwind: Continued defense build-up amid geopolitical tensions (Russia–Ukraine, Middle East), new U.S. defense budget prioritizing missiles, drones, strategic systems.
3. Fundamental Analysis
Growth: Revenue up ~1–1.3% YoY; recent international sales up 18%.
Profit & Margins: Operating margin improved to 13.8% (up from 10.7%), and free cash flow margin is ~6.2%.
Valuation: P/E ~21x, in line with historical norms. Reinforced by strong margins and a consistent backlog.
4. Technical Analysis & Momentum
Price Position: Trading well above key moving averages—50‑day EMA (
$507), 200‑day SMA ($489), and higher shorter-term averages—signals strong upside momentum.RSI: 14‑day RSI ~77 (chartmill: ~76.25), indicating overbought—but strong trend continuation often follows.
MACD & ADX: MACD positive (~3–6+), ADX ~27–34 showing a robust and steady upward trend.
Summary Indicator Ratings: Most platforms still assign a “Strong Buy” or “Buy” rating to NOC; overall technical sentiment remains bullish.
5. Risks & What to Watch
Valuation Stretch: RSI is high; short-term pullback possible.
Debt & Execution Risks: Capital-intensive programs like B‑21 are sensitive to supply chain, cost escalation. Free cash flow margin down despite margin improvement.
Sector Volatility: Lockheed Martin's
earnings were disappointing, highlighting potential idiosyncratic risk in aeronautics execution.
Conclusion:
Northrop Grumman is showing strong momentum, backed by real growth and global defense demand. While short-term dips may come, the long-term story looks solid. For medium-term investors, slowly building a position, especially on any pullbacks, could be a smart move in today’s uncertain world.
Disclaimer
This article is educational only and not financial advice. Past performance is not indicative of future results. Please consult a licensed investment advisor before making investment decisions.